

House hunting gets easier when you make the biggest decisions before visiting properties. A clear budget, firm priorities, and organized touring process can prevent rushed choices. The goal is finding a home that fits your finances and everyday life. Good house hunting starts before your first showing. Set a total housing budget, get mortgage preapproval, and choose three nonnegotiable features. Compare neighborhoods before touring homes, then record condition, costs, and tradeoffs during each visit. Use inspection findings and local sales information before making an offer.
House Hunting at a Glance
| Step | What to do | Why it matters |
|---|---|---|
| Set your budget | Calculate comfortable monthly and upfront costs | Prevents shopping above your financial comfort zone |
| Get preapproved | Speak with several mortgage lenders | Shows sellers you are financially prepared |
| Set priorities | Separate needs from preferences | Makes property comparisons easier |
| Research locations | Review commute, taxes, schools, services, and risks | A home cannot be separated from its location |
| Tour carefully | Inspect condition instead of focusing on décor | Helps reveal expensive problems |
| Compare properties | Use the same scorecard after every tour | Reduces emotional decision-making |
| Prepare an offer | Review comparable sales and seller circumstances | Supports a more informed price |
| Inspect before closing | Hire a qualified inspector | Identifies issues that may affect the purchase |
Key Takeaways
* Decide what monthly payment feels comfortable before choosing a listing-price ceiling. * Mortgage preapproval can make your search more focused and strengthen your position with sellers. * Keep your true must-have list short, preferably around three major priorities. * Compare neighborhoods at different times instead of judging them during one showing. * Take consistent notes and photos so multiple properties do not blend together. * Pay attention to systems, water problems, roofing, structure, and maintenance history. * Keep money available for closing, moving, repairs, insurance, taxes, and emergencies. * Treat an accepted offer as another evaluation stage, not the end of your research.
Set Your Real Budget Before You Start Looking
Your lender’s maximum approval should not automatically become your personal spending limit. A mortgage is only one part of the cost of owning a home. Taxes, insurance, maintenance, utilities, and association fees can change the monthly total significantly. The Consumer Financial Protection Bureau recommends estimating both upfront and ongoing housing costs. It notes that closing costs often range from 2% to 5% of the purchase price. Your actual figure depends on the property, location, lender, and loan structure. Keep part of your available cash outside the purchase transaction whenever possible. Moving expenses and immediate repairs can arrive shortly after closing. An emergency reserve also gives you more breathing room after becoming a homeowner.
Get Mortgage Preapproval Before Serious House Hunting
A preapproval gives you a more useful budget than an online affordability calculator alone. A lender reviews financial information and estimates how much it may lend you. Sellers may also view a preapproved buyer as better prepared to complete a transaction. The CFPB recommends comparing several lenders instead of relying on the first option. Its mortgage guidance suggests seeking at least three preapprovals during your financing search. Comparing lenders can reveal differences in rates, fees, and loan structures. Remember that a preapproval is not final mortgage approval. Your finances and the selected property will still require additional review. Avoid major new debts or unexplained financial changes while your purchase is underway.
Create a Short Must-Have List
Long wish lists make home searches harder because few properties meet every preference. Divide your criteria into needs, strong preferences, and optional extras. Keep the true nonnegotiable category as short as possible. Your must-haves might include location, bedroom count, accessibility, or a maximum commute. Preferences could include a larger yard, renovated kitchen, or finished basement. Cosmetic details usually deserve less weight because many can change after purchase. This system also makes compromises easier to evaluate. You can quickly identify which shortcomings are permanent and which are fixable. That distinction matters when several otherwise suitable homes appear at similar prices.
Research the Neighborhood Before Falling for the House
You are buying the location along with the building. Visit promising areas during weekdays, evenings, and weekends when possible. Traffic, noise, parking, and activity levels can change substantially throughout the day. Check commute routes, property taxes, insurance considerations, local services, and nearby development plans. Families may also want to research school options using current district information. Buyers should verify factors that matter personally rather than relying only on listing descriptions. Newsprest maintains a broader Real Estate section covering property-related topics. Buyers purchasing with relatives, friends, or unmarried partners should also understand ownership structure. The site’s guide to tenants in common explains one form of shared property ownership.
What to Check During a Home Tour
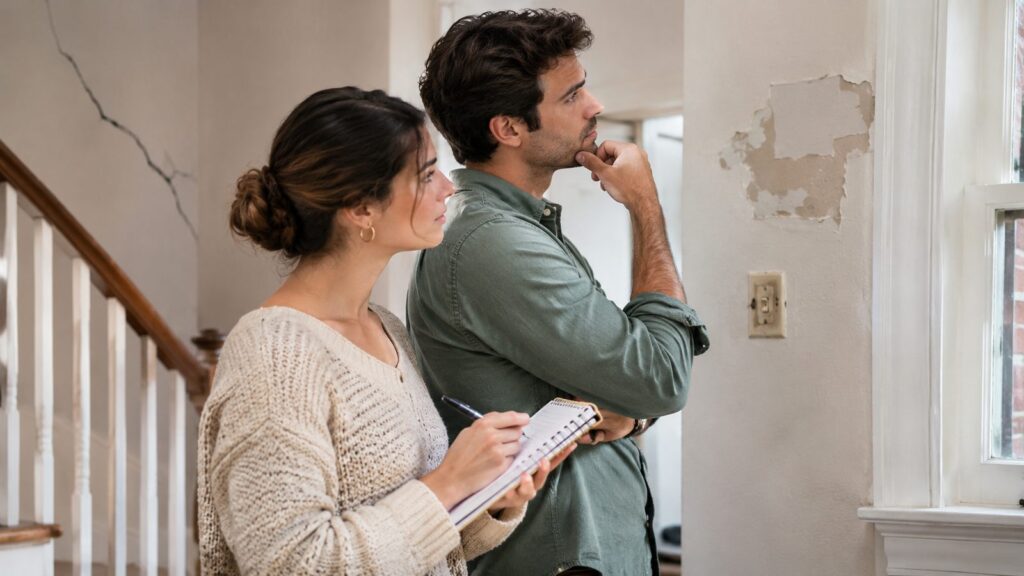
Listing photos are designed to present a property attractively. Your job during a showing is different because you are evaluating condition and suitability. Look past furniture, paint colors, staging, and decorative upgrades. Pay particular attention to these areas.
* Signs of water intrusion, staining, or persistent moisture. * Visible foundation movement or significant cracking. * Roof age and obvious exterior deterioration. * Heating and cooling system age. * Electrical panels, outlets, and visible wiring concerns. * Window and door operation. * Water pressure and plumbing fixtures. * Storage space and room dimensions. * Street noise and neighboring properties. * Drainage and grading around the home. * Parking and driveway conditions. * Signs of neglected maintenance.
A showing is not a substitute for a professional inspection. It helps you decide whether the property deserves further consideration. Serious defects should receive qualified professional evaluation rather than visual guesswork.
Use a Scorecard Instead of Relying on Memory
Homes start blending together after several tours. Create one scorecard and use it for every serious candidate. A consistent system makes emotional reactions easier to balance with practical concerns. Score location, condition, layout, recurring costs, storage, outdoor space, and renovation needs. Add a notes section for major strengths and potential expenses. Take permitted photos so you can compare important details later. You can also assign higher weight to your nonnegotiables. A perfect kitchen should not outweigh an unacceptable commute if location matters more. That simple weighting system helps prevent expensive compromises.
Separate Fixable Problems From Permanent Problems
Paint colors, lighting fixtures, and cabinet hardware are usually changeable. Lot size, street location, school boundaries, and many layout limitations are much harder to alter. Buyers often make better decisions when they separate those two categories. Estimate renovation costs before assuming a problem will be cheap to solve. A dated bathroom may be manageable, while major structural changes can become costly quickly. Ask contractors for estimates when a potential project could affect your offer. Do not let attractive staging disguise fundamental limitations. Focus first on the property’s location, structure, layout, and major systems. Decorative improvements can come later if the underlying home works.
Understand the Full Cash Needed to Buy
Your down payment is not your only upfront expense. Closing charges can include lender fees, appraisal costs, title expenses, taxes, insurance, and other transaction costs. The exact mix varies by loan and location. The CFPB’s Loan Estimate shows important mortgage costs before closing. It includes estimated payments, closing costs, taxes, insurance, and other loan information. Comparing Loan Estimates can help you evaluate competing mortgage offers. Leave room for expenses after you receive the keys. You may need movers, repairs, furniture, locks, appliances, or utility deposits. A purchase price that empties your savings can create unnecessary financial pressure.
Buying With Another Person Requires Extra Planning
Friends, relatives, or unmarried partners may decide to purchase together. Shared buying can expand purchasing power, but ownership details should be settled beforehand. Each buyer should understand contributions, responsibilities, and exit options. Ownership percentages do not always need to be equal under every ownership arrangement. State laws and deed structures can also affect inheritance and transfer rights. Professional legal advice becomes valuable when ownership or contributions are complicated. Long-term property planning may also matter after a purchase. Newsprest’s guide to trust setup costs in 2026 provides broader estate-planning cost information. Buyers should use a qualified professional for advice tailored to their state and circumstances.
Do Not Skip the Inspection
A home inspection gives you information that a normal showing cannot provide. Inspectors examine major components and identify visible defects or areas needing further evaluation. The findings can affect your willingness to proceed with the purchase. An inspection may reveal repair needs that influence negotiations. Depending on your contract and local market, you may request repairs, credits, or another solution. Your available options depend on the agreement you signed. Attend the inspection when practical and ask clear questions. Focus on safety concerns, major systems, expected repair timing, and maintenance needs. Use specialized professionals when the inspector recommends further evaluation.
Build an Offer Around Evidence
A strong offer is not always the highest offer. Price, financing strength, contingencies, closing timing, and seller priorities can all influence acceptance. Your agent can help explain local practices and recent comparable sales. Avoid increasing your offer simply because you feel attached to a property. Decide your maximum acceptable price before negotiations become emotional. That limit should reflect both the home’s value and your financial comfort. Market conditions vary by city and even neighborhood. Some sellers may have several competing buyers, while others may negotiate after longer listing periods. Use current local evidence instead of broad national headlines when setting your strategy.
Know When to Walk Away
Finding a property you like can make serious problems easier to rationalize. Keep your original budget and nonnegotiables visible throughout negotiations. Walking away can be the better choice when new facts change the value proposition. Major inspection problems, unaffordable payments, unclear ownership issues, or excessive renovation costs deserve careful attention. A house does not become affordable because you spent weeks searching for it. Past effort should not determine your next financial decision. There will always be tradeoffs in a home purchase. The useful question is whether those tradeoffs fit your priorities and resources. A good purchase should remain workable after the excitement of closing fades.
Frequently Asked Questions About House Hunting
How long should you spend looking for a house?
There is no fixed timeline that works for every buyer. Inventory, financing, location, and your requirements all influence search length. Give yourself enough time to compare properties without using an arbitrary deadline to force a purchase.
Should you get preapproved before looking at houses?
Preapproval is useful before you begin touring homes seriously. It provides a lender-reviewed borrowing estimate and can show sellers that financing is being prepared. It does not guarantee final approval, so keep your finances stable during the purchase process.
How many homes should you tour in one day?
Fewer focused tours are often more useful than an exhausting schedule. Touring several homes back-to-back can make details harder to remember. Keep notes and use the same checklist after each property.
What should first-time buyers look for during a showing?
First-time buyers should focus on condition, layout, location, and likely ownership costs. Check visible signs of moisture, structural concerns, aging systems, noise, storage, and maintenance. A professional inspection should follow when you move forward with a property.
What are the biggest house hunting mistakes?
Common mistakes include shopping above your comfortable budget and focusing too heavily on cosmetic features. Buyers can also overlook location problems or compare homes without consistent criteria. Skipping professional inspections or ignoring ownership costs can create expensive surprises.
Make Your Search a Decision Process
The right home is not necessarily the property with the most impressive photos. It is the one that best balances affordability, location, condition, and your actual priorities. A structured search gives you a better way to identify that balance. Start with financing, then define your needs and research target neighborhoods. Use the same checklist during every serious tour and investigate major concerns before offering. That approach makes your final decision easier to defend financially and practically. Keep your search focused without expecting perfection. Most buyers will compromise somewhere, but those compromises should be deliberate. When the numbers and property both make sense, you can move forward with much greater confidence. —
